Is Your Home Insurance Keeping Up with Value?
Asset Protection, Homeowners Insurance
Homeowners Insurance Review: Is Your Coverage Keeping Up With Your Home's Value?
Your home may be worth far more today than when you bought it—but is your homeowners insurance keeping pace, or quietly falling behind?
Why a Homeowners Insurance Review Matters in 2026
Over the last few years, home values and rebuilding costs have climbed sharply in many parts of the country. At the same time, climate-driven disasters and construction inflation have pushed the cost of each claim dramatically higher. A 2026 trends report from LexisNexis found that claim severity has jumped more than 90% compared to 2019, even as people file fewer claims overall. That means it is more expensive than ever for an insurer to rebuild a damaged home—and more dangerous than ever to be underinsured.
Meanwhile, premiums themselves have been volatile. Depending on the source, the national average homeowners premium in 2026 ranges roughly from $2,100 to $3,500 per year for typical coverage levels, with some states like Florida averaging more than $8,000 to $10,000 annually and others, such as Hawaii, below $1,000. In this environment, it is tempting to focus only on price. But a smart homeowners insurance review starts with one key question: “Would my current policy actually cover the cost to rebuild my home today?”
Step 1: Check If Your Dwelling Coverage Matches Today's Rebuild Cost
The heart of a homeowners policy is dwelling coverage—the amount your insurer will pay to repair or rebuild the structure of your home after a covered loss. Many people assume this number automatically tracks their home's market value. It does not. Market value includes the land and local demand; your policy needs to reflect reconstruction cost, which is driven by materials, labor, and building codes where you live.
If you bought your house ten years ago for $250,000 and insured it for that amount, but it would now cost $375,000 to rebuild because of higher lumber and labor prices, you could be short by more than $100,000 after a major fire. The Insurance Information Institute recommends reviewing your homeowners coverage regularly to keep it aligned with current rebuilding costs, especially after big renovations or additions. An annual review with your agent or an online replacement cost estimator can reveal whether your dwelling limit is overdue for an update.
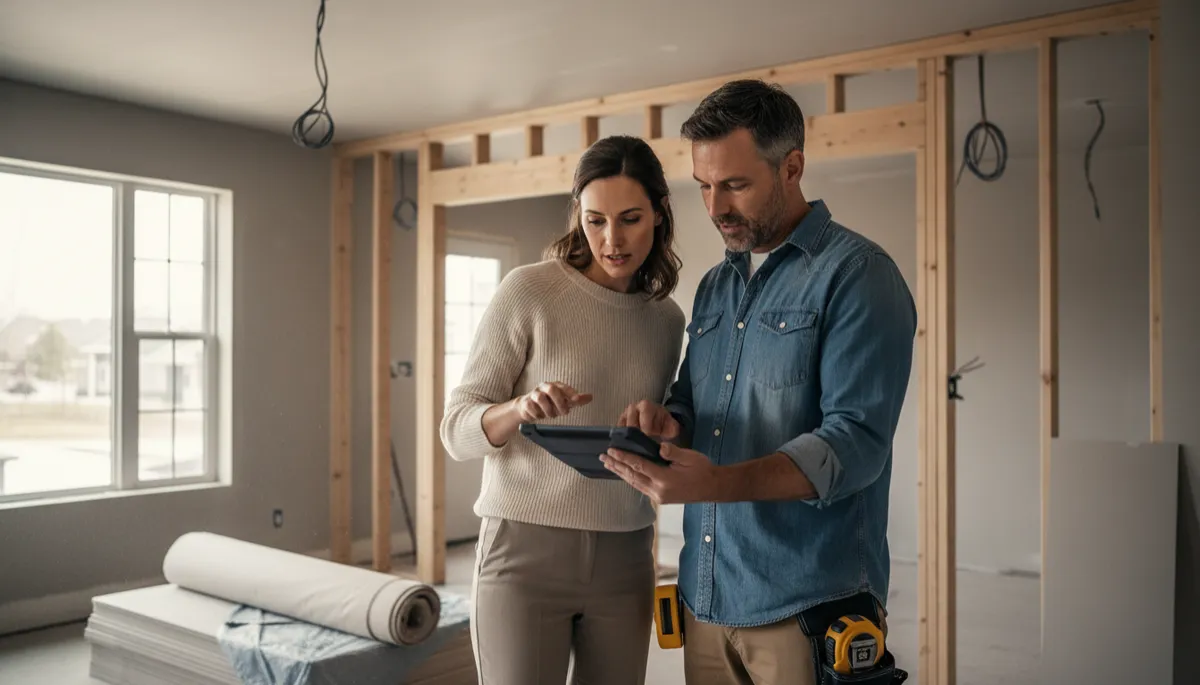
Major renovations can outgrow your original policy limits if you do not update coverage.
Step 2: Make Sure Other Key Coverages Keep Up Too
A thorough homeowners insurance review goes beyond the dwelling limit. As your lifestyle and assets grow, other parts of your policy may also lag behind your real risk:
Personal property: This covers your belongings—furniture, clothing, electronics, appliances, and more. Many policies set this automatically at a percentage of your dwelling coverage, but that may not reflect reality. If you have upgraded to high-end electronics, custom furniture, or new appliances, take a fresh inventory and compare it with your current personal property limit.
Valuable items: Jewelry, art, collectibles, and some electronics often have sub-limits—maybe only a few thousand dollars for theft. If you have an engagement ring, designer watches, or rare collectibles, you may need separate riders or a scheduled personal property endorsement to be fully protected.
Liability protection: As your net worth grows, so should your liability coverage. This protects you if someone is injured on your property or you cause damage to others. Standard limits like $100,000 are often too low for today’s legal costs. Many homeowners now choose $300,000 to $500,000 or even add an umbrella policy for extra peace of mind.
Additional living expenses: If a covered loss forces you out of your home, this coverage helps pay for hotel stays, rent, and extra costs. With rental prices climbing in many cities, verify that your limit would realistically cover several months of alternative housing.
Step 3: Revisit Perils, Exclusions, and Location Risks
Standard homeowners policies cover common perils like fire, theft, and certain types of storms—but not everything. Floods and earthquakes, for example, are usually excluded and require separate policies or endorsements. With climate-related disasters becoming more frequent and costly, it is worth asking whether your risk profile has changed since you last reviewed your coverage.
From 2019 to 2024, some coastal and high-risk regions saw premiums jump 25% or more, while other states experienced flat or even declining rates. If you live in an area prone to wildfires, hurricanes, or severe storms, your insurer may have tightened terms, raised deductibles for wind or hail, or added new exclusions. Reading the fine print—or having an agent walk you through it—helps you avoid surprises when you need your policy most.
💡 Pro Tip: Ask your agent to explain any special deductibles (like separate wind or hurricane deductibles) and whether flood or earthquake coverage makes sense for your location.
Step 4: Balance Premiums, Deductibles, and Discounts
Once you know your coverage is adequate, you can fine-tune cost. In 2026, national premium increases are finally slowing, and more homeowners are seeing flat or even lower renewal rates. Still, what you pay depends heavily on your coverage level, deductible, and risk profile. Raising your deductible can lower your premium, but be sure you could comfortably pay that amount out-of-pocket after a loss.
Also explore available discounts: bundling home and auto, installing security systems, upgrading your roof, or adding smart leak detectors can all help. With more insurers actively competing again in many markets, shopping around at renewal can uncover better value without sacrificing protection. Just remember, a slightly cheaper policy is not a win if it leaves a six-figure gap between your coverage and your home’s true rebuilding cost.
How Often Should You Review Your Homeowners Insurance?
Many experts, including Forbes Advisor, recommend reviewing your homeowners policy at least once a year, and sooner if you experience a major life or property change. You should schedule a review when you:
Complete a renovation, addition, or major system upgrade (like a new kitchen or finished basement)
Purchase expensive items such as jewelry, art, or high-end electronics
Add risk factors like a swimming pool, trampoline, or home-based business
Notice significant changes in local construction costs or home prices
The Bottom Line: Protect the Home You Have Today, Not the One You Bought Years Ago
A homeowners policy is not a set‑it‑and‑forget‑it document. Your home’s value, the cost to rebuild, and the risks around you are all moving targets. A focused homeowners insurance review—checking dwelling limits, personal property, liability, exclusions, and deductibles—helps answer the crucial question: “Is my coverage truly keeping up with my home’s value?”
Taking an hour each year to review your policy, compare quotes, and adjust limits is a small investment compared to the financial shock of discovering you are underinsured after a disaster. Talk with your agent, ask pointed questions, and do not be afraid to switch providers if another company offers stronger protection for a similar price. Your home is likely your largest asset—make sure your insurance is large enough to match it.
Still have questions? Let's schedule a quick 15 minute call to discuss your needs https://calendly.com/bnhre/new-meeting.
Get your COMPLIMENTARYHome Valuation and Home Selling Guide at timbeary.realtor