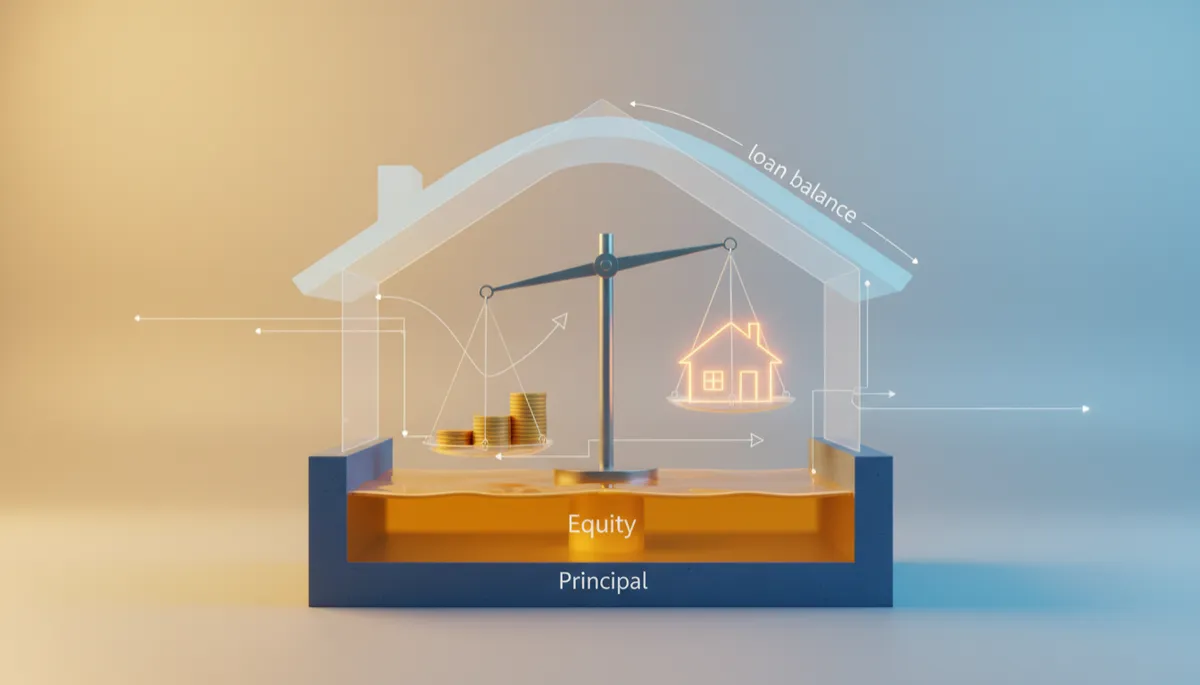
Understanding Home Equity: Calculate Your Value
Personal Finance, Home Equity
Home Equity 101: How Much Do You Actually Have, and How Do You Find Out?
Your home might be your biggest asset, but many homeowners aren’t quite sure how much of it they truly “own.” That’s where home equity comes in. Understanding it can help you borrow smarter, plan for the future, and feel more confident about your financial picture.
Home Equity 101: What It Actually Means
At its simplest, home equity is the portion of your property that you truly own, free and clear of the bank. It’s the difference between what your home is worth today and what you still owe on your mortgage and other home-related loans secured by the property.
Think of your home as a pie. The full pie is your home’s current market value. The slice the lender still “owns” is the unpaid balance on your mortgage. Whatever is left is your equity—your slice of the pie. As you pay down your loan and as your home’s value rises over time, your slice ideally gets bigger.
📌 Key Takeaway: Home equity is not what you paid for the house; it’s what the house is worth now, minus what you still owe.
Building equity matters because it can be a powerful financial resource. People often tap their equity to:
Fund renovations or repairs
Consolidate higher-interest debt
Help pay for education or major life events
Strengthen their net worth and retirement plan
How Much Home Equity Do You Actually Have?
The good news is that calculating your home equity is more straightforward than it sounds. You don’t need to be a math whiz—just follow a simple formula:
Formula: Home’s current market value − Total mortgage and home loan balances = Your home equity.
Imagine your home is worth $450,000 today. You still owe $280,000 on your main mortgage and $20,000 on a home equity line of credit (HELOC). Your total debt secured by the house is $300,000. Subtract that from $450,000, and you have $150,000 in home equity.
-toned photo of a financial advisor and homeowner sitting at a desk reviewing printed home value...
A simple breakdown of value minus debt turns a vague guess into a clear equity number.
It’s also useful to think in percentages. Lenders often talk about loan-to-value ratio (LTV), which compares how much you owe to what your home is worth. In the example above, owing $300,000 on a $450,000 home means an LTV of about 67%. That also means you have roughly 33% equity. Many lenders prefer you to have at least 15–20% equity if you want to borrow against your home at competitive rates.
💡 Pro Tip: As your equity grows past 20%, you may be able to remove private mortgage insurance (PMI), which can lower your monthly payment.
How Do You Find Out Your Real Home Equity?
The key to knowing your equity is having realistic numbers for both sides of the equation: what your home is worth and what you owe. Here’s how to get there step by step.
1. Pin Down Your Current Mortgage Balances
Start with what you owe—it’s usually the easiest part:
Log in to your mortgage lender’s online portal or check your latest statement for the current principal balance.
If you’ve taken out a HELOC or second mortgage, gather those statements too and note their balances.
Add all these balances together. That’s your total debt against the home today—not what you originally borrowed, but what’s left to pay off.
2. Estimate Your Home’s Current Market Value
This part takes a bit more judgment. You have several options, each with different levels of cost and accuracy:
Online estimates: Real estate websites can give quick, free value estimates based on recent sales in your area. They’re a starting point, but not perfect.
Comparative market analysis (CMA): A local real estate agent can prepare a report comparing your home to similar properties that have sold recently. Many offer this at no cost if you’re considering selling or refinancing.
Professional appraisal: For the most accurate picture, especially if you’re applying for a loan, a licensed appraiser can provide a formal valuation, typically for a few hundred dollars.
⚠️ Warning: Don’t rely on what you “hope” your home is worth. Overestimating value can make you think you have more equity—and more borrowing power—than you really do.
3. Put It All Together
Once you have both numbers, subtract your total mortgage and home loan balances from your estimated market value. The result is your current home equity in dollars. Divide your equity by your home’s value to see it as a percentage.
It can be helpful to repeat this exercise once or twice a year. Markets change, and so does your loan balance as you make payments. Tracking your equity over time can show you how your financial position is improving—and whether you’re getting closer to big goals, like selling, refinancing, or retiring your mortgage altogether.
Turning Your Equity Knowledge into Smart Decisions
Knowing your home equity isn’t just a number to file away. It can influence how you approach debt, savings, and long-term plans. With a clear picture of how much you actually own, you’re better equipped to decide whether to tap into that equity, protect it by avoiding over-borrowing, or focus on paying down your mortgage faster to build it up.
Your home is more than a place to live—it’s a cornerstone of your financial life. Understanding your equity is the first step in making sure it’s working for you, not just sitting on the sidelines.
Still have questions? Let's schedule a quick 15 minute call to discuss your needs https://calendly.com/bnhre/new-meeting.
Get your COMPLIMENTARY Home Valuation and Home Selling Guide at timbeary.realtor